Showing posts with label money. Show all posts

Saturday, June 30, 2012

2012 Financial Goals: Update


It's been a long time since I've done one of these but I'm back! I have had a lot of changes to my finances, mainly I'm in the process of buying my first home!  From a purely financial standpoint this may not have been the best decision, however the home is in an ideal neighborhood, I LOVE the house and can see myself (and my fiance and future family) there for a long time, so I'm comfortable with my choice.


Save $4000 by January 2013 I've added about $2200 to my savings this year and so far I haven't touched any of the money that has been added to my savings account since I opened it.  I'm scheduled to close on the house in about 2 weeks and unfortunately I will have to pull out about $1500 for closing.

Maintain a buffer of $100 in my monthly budget. From March to May I maintained about a $400 buffer each month.  In June I went on a vacation and had some minor expenses relating to the house (ex paying for a home inspection) so this buffer was only $49.  I did put down a $1000 deposit to secure the venue for my wedding next year, but I didn't include this in my monthly budget because I have been saving cash and gifts from family members in an envelope labeled Wedding Fund (old school, I know).

Maintain $0 credit card debt.
I used my credit card for my regular monthly expenses (grocery, gas, etc.) and pay the balance in full by the end of the month.  So far this year I've gotten a $50 Gift Card using my credit card reward points and by next month I should have enough points for another $25 card!

Open a Roth IRA
Haven't done this yet. 

Monday, March 26, 2012

Money Lesson: Stay Busy

source

I love the feeling of having plans.  Nothing is more exciting--or makes the workweek go by more quickly--than having something to look forward to on the weekend. I also find that having weekend plans keeps my spending in check.  On the days where I have nothing to do, my boredom leads me to the mall or browsing the aisles of Target...and we all know how tempting it is to spend once you set foot in the stores!

I've also noticed that I'm more prone to constant snacking and mindless eating on those lazy days where I just stay in the house reading blogs and watching Netflix.  There's a saying that goes "the Devil finds work for idle hands to do” and I think there may be a little truth to it.  When there is something on my calendar, even if it's something like a visit from family or plans to attend an event, I'm usually occupied for a number of hours, engaged in some activity that doesn't require me to spend money, and I'm not even tempted to spend any money.  Sometimes I get engrossed in a good book or working to craft a blog post and the next thing I know, I've had a "no-spend" weekend!

If you are like me and are tempted to shop out of pure boredom, find ways to stay busy! Visit your loved ones, spend more time on hobbies, and find budget-friendly activities to occupy your weekend!

Friday, March 9, 2012

Money in your 20s: 5 Things Everyone Should Know

Women's Money Week 2012 Participant

I am participating in the first annual Women’s Money Week, a project to empower women to take control of their finances.   Today's topic is Money in your Twenties/Thirties/Forties/Fifties/Retirement. Check out the Women's Money Week 2012 website for more posts from some amazing Women Money Bloggers!    

For some this period may represent your glory days while others may refer to it as a Quarter Life Crisis, but your 20s is a time of amazing transformation. The bridge connecting adolescence and adulthood, your 20s may bring your first (full-time) job, first love, first major purchase (ex- a new car), and first experience with recurring bills (student loans anyone?).  With all these “firsts,” it is important to make sure you are making smart choices and creating good habits to carry you through the rest of your life…ESPECIALLY when it comes to your finances.    Here are a few things that I believe everyone should know about money before leaving your 20s to put you on the path to financial security:

How to create a budget.
You have probably heard this before, but the budget is one of the basic principles of personal finance. For some, this may be your first experience making enough money to actually support yourself.  In order to manage this new fortune, you need to keep track of the money you have coming in (income), the money you have going out (expenses), and make sure that your income is always greater than your expenses.  

Avoid the credit trap!
When I was in college, there were credit card companies all over the campus offering free t-shirts, mugs, etc.  just for signing up.  In that setting I was eager to sign up for my first credit card, but luckily I refrained from actually using the card for over a year and truly considered it a tool to be used for emergencies (and the occasional tattoo—don’t judge me lol).  Your 20s is a time for establishing and building your credit. Because you probably have little to no credit already, you probably won’t have the best credit rates, so spending recklessly on your card and carrying a credit card balance from month to month means that you may face hefty interest charges.  That spring wardrobe you caught on sale might not be that good of a deal if you buy it on credit and have to pay an extra 10-20% over the course of a year.  Also, don’t mess up your credit early by applying for a lot of different credit cards, maxing out card, and missing payments.  Not only do these immediately hurt your credit score (which would affect your future interest rates on home/auto loans), but they create bad financial habits that become more and more difficult to break.

Friday, March 2, 2012

2012 Financial Goals: February Update


Save $4000 by January 2013 I contributed $210 to my savings account this month through automatic direct deposit. I also took part of my tax refund along with some of my "buffer" in my checking account and added $600 to savings, so I've already saved about $1000 so far this year!

Maintain a buffer of $100 in my monthly budget. I've really been sticking to this one, and February was almost as good as January.  By the end of the month I had an extra $650 left over after expenses and savings!

Maintain $0 credit card debt.
I used my credit card for my regular monthly expenses (grocery, gas, etc.) and paid the balance in full by the end of the month.

Open a Roth IRA
Haven't done this yet. 

Thursday, February 23, 2012

Money Lesson: Stop Torturing Yourself

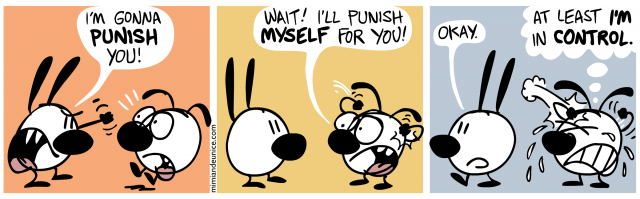
i'm gonna punish you / wait i'll punish myself for you / okay. at least i'm in control

 I have a confession...sometimes I procrastinate and allow issues to linger instead of tackling them right away. A few weeks ago, I was working on a task at my job but I just could not get myself to take the actions needed to finish it. For some reason, I felt this task was so daunting and so time consuming that I just wanted to avoid it at all costs. i knew I would have to finish the project eventually, but at the time I chose to let it sit on my desk for a few days while I kept myself busy with other work that was equally as important but probably less urgent. The problem is that each day it sat on my desk, my anxiety regarding the work increased and what should have been a proverbial "molehill" quickly became a "mountain" in my head. Finally, one day I came to my senses. I asked myself, Why am I spending all of this time agonizing over this work when I can just buckle down and finish it?

I've created similar scenarios while working on my finances. I know I have spent more hours worrying about how much I owe in studnt loans than actually creating a solid plan to pay them off quickly. I've purchased items that I quickly realize that I will never use, but instead of going to get a refund, I would just put things away in my closet as I worry about going over my budget for the month.

 Some of you may have the same problem that I have of putting myself through unnecessary suffering. Do you find ourself avoiding the mailbox because of the many final notices you get, or notice your heart racing when the phone rings for fear that it may be a bill collector...BUT you go shopping every weekend faithfully(and never coming home empty handed, might I add)? Or maybe you feel yourself drowning in debt, but rather than reaching out for assistance (negotiating new loan terms, exploring economic hardship provisions, getting credit counseling or financial planning assistance) you suffer in silence  day after day.

 Well I'm here to tell you: Stop torturing yourself! Do whatever is needed to rid you of the burden of your financial worries. Action is the first step in obtaining freedom, so imagine how good you will feel when you trade in your procrastination, avoidance, and associated stress for knowledge, progress, and ultimate achievement!

Tuesday, January 31, 2012

2012 Financial Goals: January Update


Save $4000 by January 2013 I contributed $210 to my savings account this month through automatic direct deposit. In the next week or so, I will transfer a lump sum ($300-500) into my savings account. Wondering where I'm going to get that lump sum? Keep reading...

Maintain a buffer of $100 in my monthly budget. I did a great job of limiting my shopping and my restaurant meals this month.  I went out to eat only 4 times this month and what shopping I did was from the clearance rack.  By the end of the month I had an extra $700 left over after expenses and savings!

Maintain $0 credit card debt.
I used my credit card for my regular monthly expenses (grocery, gas, etc.) and paid the balance in full by the end of the month.

Open a Roth IRA
Haven't done this yet. 

Thursday, January 5, 2012

Money Lesson: Don't Eat The Cookie!

Recently I shared some of my financial goals for the year, but I didn't tell you all about the other life goals that I have. One is to improve my eating habits, and part of the way I've been doing that is to track calories and keep a food diary using the My Fitness Pal app on my iPhone. My motivation was tested when my fiance decided to make some chocolate chip cookies. I had space in my calorie count for the day to have a cookie, so of course I was ready to run in the kitchen to get one...BUT, I decided to enter the cookie into my food diary before actually eating it, and boy did this make all the difference.

The app I use tells me how much progress you can make in 5 weeks if everyday you ate like you did today (in terms of calories consumed). By eating this 150 calorie cookie and getting into the habit of "splurging" on an extra 150 calories each day, the amount of weight I can lose in 5 weeks would be decreased by 1.5lbs. This was a light bulb moment for me...when it comes to health or even money, each seemingly small decision you make is important, as they collectively form your set of habits that will either lead you to your goal, or lead you astray. That afternoon vending machine break and the weekly trip to Target that leaves you $20 poorer each time may seem like small amounts of money, but added together can really hurt your budget. 

Every time you make a bad decision, it becomes easier and easier to make another one. Also, each bad decision makes it easier to fall off the wagon of change because even though we all know that you can make mistakes along our journey, we all have had times where we accept mistakes as failure and just stop trying all together.

To commit to a lifestyle change, we have to first commit to taking the journey one decision at a time. At each "checkpoint" (decision), we have to decide whether to move closer to our goals, or to move further away. We will have missteps along the way, but we just need to work on making those mistakes occur further and further apart.

I think this commercial from Fidelity illustrates my point pretty well:


Sunday, January 1, 2012

2012 Financial Goals


It's a new year, so it is the perfect time for a new set of goals.  I made awesome strides in my financial life in 2012, and I hope to continue that success into 2012.  Here is a list of my goals for 2012, along with ideas for behaviors that I can do to help achieve them. 

Save $4000 by January 2013
  • Direct deposits to savings: Already set, with the current setting can save about $2500 without doing anything else.  May increase the amount saved each month.
  • Save 50% (or more) of tax refund.  I saved a good portion of my refund last year and used part of it to pay off credit card. 
  • Increase income.  This year I will be eligible for a promotion at work that comes with a 10% raise.  Also use money earned from Swagbucks (gift cards), online surveys, and credit card rewards to decrease some of my regular expenses instead of using it to buy frivolous stuff

Maintain a buffer of $100 in my monthly budget.  A few times in 2011 I went over my budget (note: I think of my savings as a bill I have to pay, so I didn’t actually spend more than I earned, just cut into the amount of money I put into savings each month).  After I build up a few months of a buffer I will transfer that amount to my savings account.
  • Tell myself no when I’m lusting after an item in the store
  • Limit costly restaurant meals
  • Use cash when shopping for personal supplies, clothes, food, etc to make sure I stick to the monthly budget.

Maintain $0 credit card debt. 
  • Pay credit card balance in full each month
  • For major purchases and wedding purchases, create separate savings account/sub-account to take care of it instead of using credit card.

Open a Roth IRA
  • Read blogs, books, etc to research options


Monday, December 12, 2011

Guest Blogging Round-up: November

Every Thursday, I write about all things finance from the young adult’s perspective in a series called Pennies-Nickel-Dollars over at Pretty Natural Divas.  Take a look at my posts from October and be sure to check me out  each and every Thursday! 


Pennies-Nickels-Dollars: Managing Student Loans  Tips to help you minimize and manage student loans before, during, an after college.

No Job & No Savings, Could You Survive? A look at the online game Spent that simulates the feeling financial hardship. 

5 ways cleaning out your closet can make/save you money  How to find money in your closet!

Monday, December 5, 2011

3rd Update: Short Term Goals


It's been a while (6 months!) since my last update, but I've made a lot of progress in some of my goals, mainly the financial ones!


Financial

Create a $1000 emergency fund by September 2011.  
2/11: 75% of the way there! Woo Hoo!
6/11: Savings account balance: $3175.48   Woo Hoo!!!!!!!!!!!!  I'm going to wait until September to officially set a new savings goal, but with automatic savings I should be at around $3500 even by then :)
*I almost forgot about my bank that I mentioned in the "Making Savings Fun" post,  we've raised about $54 in change lol  
12/11: On December 1st I broke the $5000 mark in my savings account!

Monday, November 28, 2011

Money Lesson: Be Observant

Last weekend, I needed to do a little shopping so I headed out to Target.  I saw a large package of toilet paper was on sale for $12 so I quickly grabbed one and headed to the checkout line.  The cashier rang up my purchase and called out the total, but as I pulled out my debit card and began to swipe, I paused..."Could you repeat that total?"  Turns out the toilet paper rang up as the original price of $15...


The same night, my fiancé and I decided to go out to eat.  We had great food, a really nice waitress, and everything was going fine...until the bill came.  There was an extra item listed on our receipt and--had I not noticed--we would have been overcharged by about $5!


So, there were mistakes on two separate occasions in the same night that could have cost me money...BUT, by paying attention as the transactions were taking place, I was able to catch these mistakes and save a few dollars.  It may not seem like $3-5 is a lot of money, but considering all the purchases you make every single month, if even a few result in you being overcharged then that $3-5 can add up!  Make sure you observant when making purchases and review all your receipts!


Thursday, November 10, 2011

Guest Blogging Round-up: October

 Every Thursday, I write about all things finance from the young adult’s perspective in a series called Pennies-Nickel-Dollars over at Pretty Natural Divas.  Take a look at my posts from October and be sure to check me out  each and every Thursday! 


Daily Deal Sites: Do's and Don'ts  Tips to make sure you are making the most out of daily deal sites like Groupon and Living Social. 


Budgeting 101 + Free Budget Template A beginner's guide to making a budget, with a free template available for download.


Things Retailers Don't Tell You  A discussion of insider retail secrets used to trick shoppers into spending more.  


My Favorite Cheapie Hair Products  A rundown of my favorite hair products priced under $10.


Monday, October 31, 2011

Layaway: Good, Bad or In Between?


With the holiday season quickly approaching, I’ve noticed some major retailers advertising the return of their Layaway programs. These programs work by allowing a customer to make a small down payment on items they want to buy, and make a series of payments over the course of a few weeks to finish paying for the items. In return, the retailer will guarantee that the item is in stock when it comes time for the customer to pick it up after the last payment is made. There is a service fee associated with layaway, and a customer may be faced with cancellation fees if they miss payments or decide to cancel the layaway plan. However, from looking at both the Walmart and Kmart layaway plans, service fees generally are between $5-10, and customers can get a refund if they decide to cancel the layaway.

I’ve never used layaway before and I’m not planning to use it in the future, but I am curious to know if it is a truly a benefit for shoppers. I can think of a few “pros” for using layaway:

Thursday, October 6, 2011

Wedding Cost Estimator + My Wedding Budget


In the many hours I've spent googling wedding stuff, I found a really cool Wedding Cost Estimator tool.  The website CostOfWedding.com has polled women all across the country about their wedding expenditures, and used their responses to create a wedding cost calculator that factors in your location.

Click to go to the calculator

Just enter your zip code, answer a few questions, and with just a few clicks the tool will spit out a cost estimate for your wedding that you can print or export to an Excel spreadsheet.  Here's my estimate based on the info I put in:

Sunday, October 2, 2011

Guest Blogging Round-up

For the past month, I’ve been a guest blogger at Pretty Natural Divas.  Every Thursday, I write about all topics finance from the young adult’s perspective in a series called Pennies-Nickel-Dollars.  Take a look at my posts from September and be sure to check me out  each and every Thursday! 

Startingyour financial journey in 4 easy steps A beginner’s guide to creating new financial habits
What’sYour Shopping Style?  Find your unique approach to shopping and how to overcome the pitfalls associated with your shopping style
Pennies-Nickels-Dollars:Financial Role Models  Lessons learned from my financial role models
Pennies-Nickels-Dollars:Hair Splurge!   Reflections on a recent hair product purchase

Wednesday, September 28, 2011

What about your Friends?

"If every player in your clique is rich your clique is rugged
Nobody will fall cause everyone would be each others crutches" -Jay-Z


Like the old saying “birds of a feather flock together,” you can tell a lot about a person by looking at who they spend the most time with.  Think about your core group of friends…you shop together, eat together, and share common interests.  However, some of your bonding activities might be hurting your wallet, and steering you away from your financial goals.  The regular girls' night out at the hot downtown restaurant or the weekly shopping excursions may be fun, but once you start monitoring your spending, you may find that A) you can’t afford it! or B) it’s hard to say no to these indulgences when everyone else is doing it...after all, it's what you guys normally do! 


So what do you do now?  Decline all invites from your crew? Replace your old friends with new frugal ones? No!

Wednesday, September 7, 2011

September Dine In Challenge


This month, I'm challenging myself to eat more meals at home.   I originally just wanted to curb my fast food habit, but figured why not see if I could avoid all restaurants! For the month of September, I'm giving myself only 2 free passes to eat a meal that is not prepared at home (mine or someone else's lol).  And when I say free pass, I also mean that I'm only going to eat at a restaurant if I can eat for free.  September is my birthday month, so I've racked up more than a few birthday coupons giving me free items.  Now free items are good, but a free meal is even better! With that being said, I'm planning to use a birthday certificate for Steak 'n Shake that gives me a free double steak burger with fries. Also, during the week of September 6th through 10th, Chick-Fil-A is offering a free breakfast entree, so I will probably use that as my other free pass.

Hopefully by the end of the month I'll save both money and calories, and maybe even become a better cook!

Feel free to join me! It's never too late!

Thursday, August 11, 2011

Loaning Money Without Ruining a Relationship

In every relationship, there is a pivotal event that forever changes the course of that relationship.  One such event is "The First Request for a Loan".  Many friendships have ended, and families have torn apart over money, so it is no surprise that introducing the topic of money into any relationship can be a serious and stressful occasion.  But loaning money to a friend or family member doesn't have to result in a ruined relationship.  Follow these tips when considering giving a loan to a loved one, and you will be able to get through this process without hurting the relationship:


Wednesday, July 20, 2011

Extra income without work?

I ran across this article on Yahoo about Ways to Make Extra Income Without Much Work (link to article).

Now I can see why someone would rent out a portion of their home as a source of income.  I'm a huge HGTV fan and I love the show Income Property, which shows homeowners converting part of their homes into apartments and often earning enough rent money each month to cover their mortgage.  The idea of living rent/mortgage free is very appealing, and could make up for having to give up some my living space (that is, if I had a basement or 2nd floor, don't think I'm ready to go back to roommate living for a while lol).

source

But one thing the article mentions that I had never heard of is rent out your car.  From liability issues, to maintenance costs, and even the stress of wondering where my car is while I'm not using it, I just don't think the benefit could be worth the  risks.  The article mentions car owners earning about $200 a month and can set their own rates, but it seems like they wouldn't be able to set their rates too high (otherwise people would just rent  from a regular rental agency).  Maybe I should research into this a little more, but for now, I'm not sold on the idea.

Source 


Would you consider renting out your car? What are some other ways to make money without much work or effort? Let me know :)

Sunday, June 19, 2011

Savings Sunday 6/19/11


Every Sunday, I will feature one easy, painless, money saving tip. 


Today's Tip: Save money on phone calls.  If you use a cell phone, avoid going over on your monthly minutes (and avoid overage costs) by signing up for free nights and/or weekends and make the bulk of your calls during those times.  Also, use free online services like Skype which provides free audio and video chats to your friends using a computer, smartphone, or tablet device.  You can also use Skype to make calls to a phone line and even make international calls for a small fee.  

Hope you find a way to incorporate today's tip into your routine this week!